

1.Introduction
Did you know NRI Investment crossed $15 Billion in 2025? This shows NRIs are still in touch with their roots and have the intent to continue their legacy. But what happens to these investments after generations? How do you maintain them and pass them on?
Opening an old family cupboard and finding not just memories, but property papers, bank details, shares, and a pile of rules you never knew existed. That is exactly how inheritance feels for many NRIs. What looks like a promised gift often turns into a homework assignment filled with legal terms, tax rules, and confusing forms. Learn about your inheritance and inheritance taxes before its too late.
Many people believe inheritance in India is simple. You receive the asset, and you are done. Sadly, the law has other plans. While India does not have a direct inheritance tax, Inheritance Taxes for NRIs become tricky when income starts flowing from those assets. Rent from a house, interest from fixed deposits, dividends from shares, or money earned after selling property can all attract tax. Add FEMA rules, repatriation limits, and paperwork, and things can get overwhelming very quickly.
The biggest problem is not the tax itself, but not knowing the law. Missing deadlines, misunderstanding holding periods, or depositing money in the wrong account can lead to penalties and stress.
This blog explains Inheritance Taxes for NRIs in a simple way, so you can understand the law, avoid common mistakes, and handle inherited assets in India without panic or confusion.
2. The Legal Process and Inheritance Taxes for NRIs
Now comes the part everyone skips and then regrets later. The law and the process. Do not panic. This is not rocket science, just some basic knowledge.
First, let us talk about the laws involved for NRIs inheritance in India. One is the Foreign Exchange Management Act, 1999, also called FEMA. The other is the Income Tax Act, 1961. FEMA decides what you are allowed to inherit, hold, sell, and send outside India. The Income Tax Act decides when you have to pay tax and how much.
Under FEMA, NRIs, PIOs, and OCIs are allowed to inherit both movable and immovable assets in India. This includes houses, flats,,, bank accounts, shares, jewellery, and even art. No special RBI permission is required in most normal cases. So yes, the law is actually helpful here.
Next comes the tax part. Here is the good news. India does not have an inheritance tax. You do not pay tax just because you inherited something. The bad news is that tax appears the moment the asset starts earning money or you sell it. If you inherit a house and keep it self-occupied, there is no tax. If you rent it out, the rent becomes taxable in India. If you inherit shares, mutual funds, or fixed deposits, the dividend or interest you earn is taxable as income from other sources. The asset is free, but the income is not.
Now, selling inherited assets. This is where most people get confused. When you sell inherited property, capital gains tax applies. The holding period of the previous owner is also counted. This usually means inherited assets qualify as long-term assets. For property, long-term means more than 24 months. For shares, it is usually more than 12 months. The cost of acquisition is taken as the cost paid by the previous owner.
After selling, the money must be credited to your NRO account. From there, FEMA allows NRIs to repatriate up to USD 1 million per financial year, subject to documentation like Form 15CA and 15CB. Agricultural land sale proceeds cannot be freely repatriated .
In simple terms, the process is this : Inherit the asset legally. Understand whether it earns income. Pay tax on that income. If you sell it, calculate capital gains correctly. Deposit money in the right account. Repatriate only what the law allows.
Knowing this process early saves you money, time, and a lot of unnecessary drama later.
3. Protect Your Assets Before It Is Too Late
If you think your inherited property is safe just because you own it on paper, think again. As an NRI, you are a prime real-estate target for fraudsters, and paperwork glitches. Courts in India have repeatedly flagged this unlucky reality.
The Punjab & Haryana High Court has openly called the rising trend of property fraud against NRIs “disturbing,” noting how absentee owners are easily exploited through forged documents or misuse of powers of attorney to sell their land at fire-sale prices while they are overseas.
Actual criminal cases show this isn’t theoretical. Earlier this year in Gurgaon, seven people got three-year prison terms for forging documents and illegally selling two plots owned by an NRI, exploiting her long absence. In Dehradun, police booked 27 people for allegedly forging land papers and selling an elderly NRI woman’s property without her knowledge
Even when your legal title is solid, bureaucratic slip-ups can cost you. Just how an NRI had to fight a ₹46 lakh tax demand because the buyer used the wrong tax form after selling his property, dragging him into the Delhi High Court.
What’s the lesson here? Without asset protection, registered powers of attorney with strict limits, regular physical or legal check-ins, proper mutation and documentation, and proactive court filings like probate, your assets can be stolen or tied up for years, and getting them back is a costly, emotionally draining task . As an NRI you are not just holding property, you’re defending it.
4.Managing Your Assets Seamlessly with Mitt Arv
This is where structured planning stops being optional and starts becoming survival. For NRIs, protecting assets is not just about ownership. It is about visibility, control, and continuity across borders. This is exactly where Mitt Arv steps in.
Mitt Arv helps NRIs protect their Indian and global assets through the secure Asset Vault. Think of the Asset Vault as a single, organised digital locker where all critical documents are stored. Property papers, wills, nominations, bank details, investment records, insurance policies, and tax documents are stored in one place, securely and access-controlled. No missing papers, no confused heirs, and no “we did not know this existed” moments after a crisis.
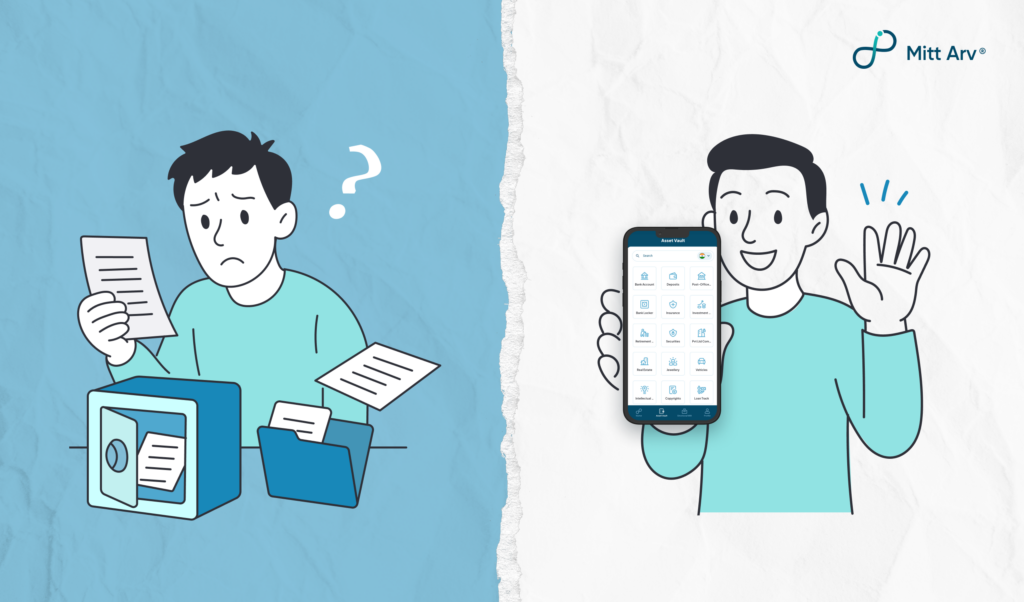
For NRIs with assets spread across countries, Mitt Arv offers multi-country access. This ensures that assets held in India, the US, UK, or elsewhere are documented under one unified structure. Each asset clearly contains ownership details. This reduces conflicts between jurisdictions and prevents assets from getting stuck in legal issues.
Most importantly, Mitt Arv ensures continuity. If something happens to the asset owner, heirs know what exists, where it exists, and how to claim it legally. No guesswork.
For NRIs, distance should not mean danger. With the right systems in place, your assets remain protected, controlled, and future-ready, no matter where you live.